My husband pointed at our card statement one evening and said, “What’s this?” A $25 line, in green, labeled “BRILLIANT DINING CREDIT.” We both stared at it. We hadn’t booked a single restaurant that month we could remember paying for with that card.
It was the Marriott Bonvoy Brilliant card’s restaurant credit, quietly doing exactly what the fine print promised. I like a benefit that works without me thinking about it, so let me walk you through how the whole thing works. I’ll keep every number real, and I’ll tell you the one habit I use so I never lose a single month of it.
What the $300 credit actually is
The Marriott Bonvoy Brilliant® American Express® card carries a $650 annual fee, which is the number that makes most people raise an eyebrow. My planner and I have been through the math on it, and the credits are a big part of why it holds up. The restaurant credit is one of them: up to $300 a year in statement credits, delivered as a $25 monthly credit.
That monthly structure is the part people trip over, so here’s the full list of terms, straight from the card’s rates and fees:
- You get up to a $25 statement credit each calendar month. Use it or lose that month’s $25.
- It applies to restaurant purchases worldwide, not just the United States.
- The month a credit applies to is based on the date the purchase is processed, not the date you swiped.
- It doesn’t cover gift cards, merchandise, or non-restaurant merchants, including nightclubs, convenience stores, grocery stores, and supermarkets.
- Whether a purchase qualifies depends on how the merchant categorizes itself.
- The credit can take 8 to 12 weeks to post after an eligible purchase. In practice it usually shows up faster than that.
- Both the primary cardholder and any authorized user can make eligible purchases, but the total is still capped at $300 per year across everyone.
- No registration required. Make the right purchases with the card and that’s it.
From what I’ve seen, anything coded as restaurant or dining spending qualifies. Plenty of people have had luck with food delivery apps too, as long as the merchant codes those purchases the same way. If you want to read the official terms yourself, they’re here: $300 Brilliant Dining Credit benefits from American Express.
The $25 habit I actually use
Most dining cards tempt you to spend a lot on the card just to chase rewards. I don’t want to put $1,000 of restaurant spending on the Brilliant every month just to collect a $25 credit while missing out on better rewards elsewhere. So I don’t.
Instead, I load $25 onto my Starbucks account through the app each month. A couple of days later, the statement credit for exactly that amount shows up. My balance never creeps too high, and on road trips a Starbucks stop is genuinely useful. I’m by no means a huge Starbucks fan, but the card effectively hands me $300 a year of Starbucks spending.
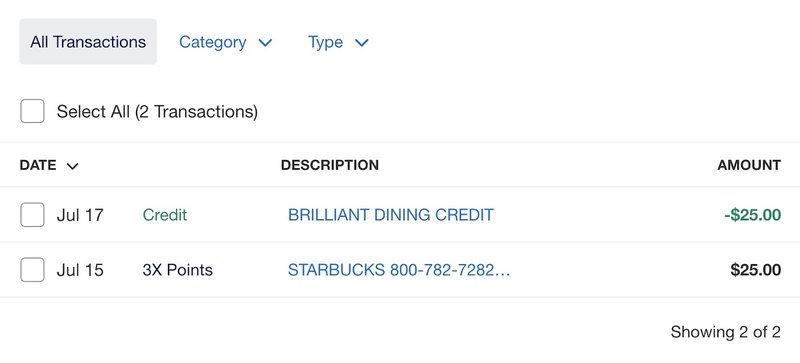
That’s the credit in action: a $25 purchase, and the matching $25 “Brilliant Dining Credit” a couple of days later. I’d expect the same approach to work with any other retailer that’s categorized in the restaurant category. The whole point is to spend exactly as much as the credit, so nothing goes unused and nothing is wasted on a card where it doesn’t earn well.
Why the $650 fee still holds up for us
The restaurant credit is worth about face value to me, which is $300 of the $650 fee gone before I even count anything else. That puts the card at roughly $350 a year in real cost. I’d happily pay $350 for the annual free night certificate alone, since it’s valid at a property costing up to 85,000 points. Everything else on the card, like Platinum Elite status and 25 elite nights toward status each year, is the icing on the cake.
None of this is professional advice, and your situation may look different. Run your own numbers before you open a card, and check the issuer’s current terms, since offers and fees change.
The bottom line: the credit is a monthly benefit, so the key is claiming all 12 months without much opportunity cost. Set a $25 monthly Starbucks top-up, spend exactly that, and you’ve just offset nearly half the annual fee on autopilot.
Try it this month: open the app, load $25 onto your Starbucks account, and watch for the credit to land in a few days. Small habits, done on a schedule, are how the fee starts to feel like a lot less.
Full disclosure: this post may contain affiliate links. If you open a card through one, we may earn a commission at no extra cost to you. Opinions are mine alone and not reviewed or endorsed by the card issuer. This is personal finance, not professional financial advice.