My husband and I had our Saturday kitchen-table talk last week. The kind where we go over the month, one envelope at a time, and I quietly add up how many small decisions we made on autopilot.
It hit me halfway through: I want better planning for the people who read this site. And I think I found a home for that — in a firm I now believe in with my whole paycheck.
Big news: I’ve joined Rialto Wealth, one of the fastest-growing independent financial planning firms in Upstate NY. Not just as an advisor — as a partner, as an owner.
My first thought was excitement. Rialto’s philosophy lines up almost word for word with what I share here every week.
- Detailed, long-term retirement planning as the center of everything.
- Investing kept simple and low-cost — no fancy machinery.
- Fiduciary and fee-only, which means one paycheck, from you, and no commission side-gig.
- Educating clients, not just serving them.
But I’ll be honest — part of me is nervous. Two toddlers at home is not the simple path to a career change. I’m making this move in large part because my husband believes in me. He’s not a “rockstar” or a “hero,” and I’m not about to pretend he is. Thank you anyway, love.
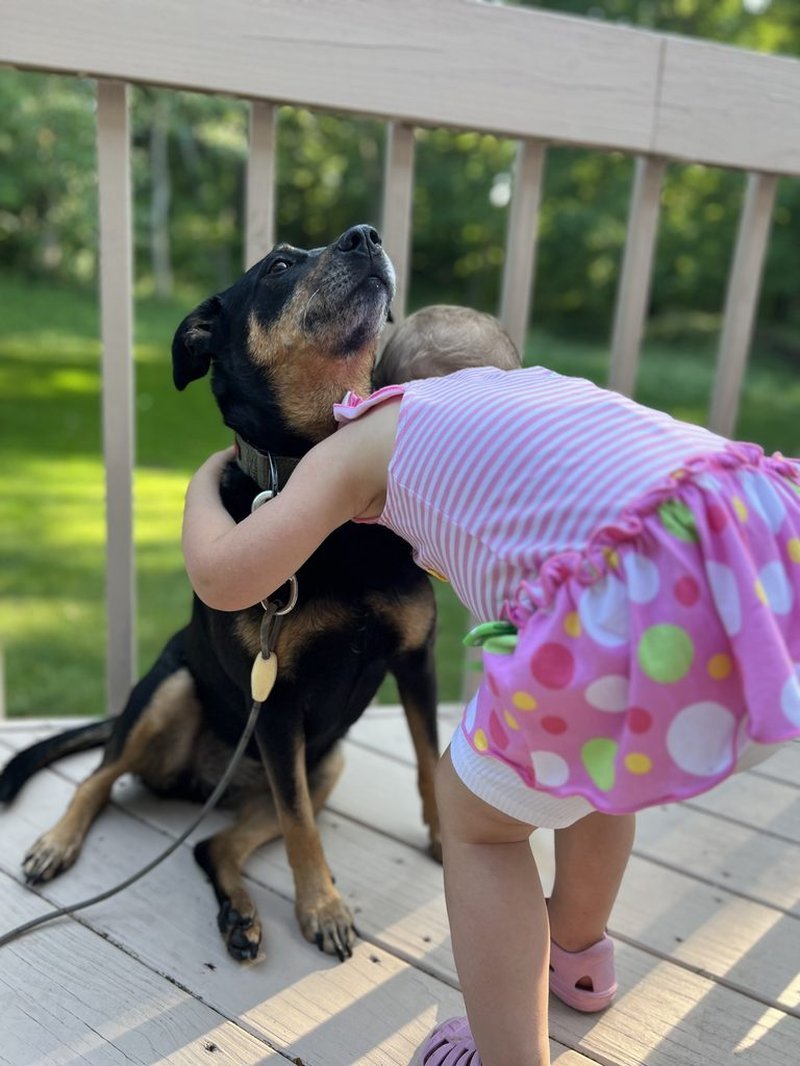
My older daughter and our dog Sadie, on the deck. This is what I’m planning around.
Why the change?
Three reasons, in the order I actually thought of them.
Trust needs independence. Clients have to be able to trust their advisor. Rialto Wealth has no shareholders and no private equity ownership — it’s 100% employee-owned. No far-away owners pressing us for quotas, no incentive to push proprietary products. That’s the commitment I’ve made to my own readers for years, and now I get to live it at work.
Simplicity beats complexity. Complex investments sound sexy, I know. Cigarettes did too, for many decades. And not coincidentally, both tend to end the same way: higher long-term costs and worse long-term outcomes. I’d rather follow Jason Zweig’s second way of making a living: “Tell the truth to those who want the truth.” (You can look up the first one.)
Smaller means better. I’m keeping my client count on the smaller side so I can spend real energy on each household. Yes, hundreds of clients fattens the margins. I’m fine trading some of that margin for clients who actually get a phone call back.
That last point is the one I want to be careful about: what I describe here is my own experience and opinion, not professional advice. Your situation is your own — run your own numbers before you decide anything.
Who is a good fit?
Here’s the honest part: Rialto isn’t for everyone. If you’re a good fit, this is what you already believe.
Retirement is the big goal. Whether you’re already retired or you’re hoping to retire in 2 or 5 or 10 years, it’s the goal you’re planning around. Everything else — Social Security timing, Medicare and healthcare, RMDs, withdrawal strategy, tax planning — orbits that.
You want an ongoing relationship. Not a one-time thought partner for a single decision. Year-over-year, as life changes.
You don’t need a stock-picker. If you want your advisor to beat the market with hot picks, we’re not the right room. If you’d rather have a low-cost, simple, academically grounded portfolio, let’s talk.
You’d rather pay less than “a lot,” but not a penny less than it’s worth. We’re not cheap. We deliberately charge less than a traditional advisor relationship — while still expecting expertise and good service.
Still deciding? You can see more on their site: Rialto Wealth’s page with full details. And yes — we’re hiring too, if you want to chat about the work itself.
Maybe you’re the one who needs the help
Maybe retirement planning has been “we’ll get to it eventually” for a while now. Maybe you’ve got questions that go deeper than which fund to own — the tax stuff, the healthcare stuff, the what-does-this-actually-mean stuff.
That’s the kind of person I built this blog for, and the kind of person I’m now planning for at work. If that sounds like you, send me a note through the contact page on their site and tell me what’s actually going on with your money. No jargon, no pressure — just your questions in plain English.
One thing you can do today
Before you decide anything about an advisor — including me — do the one exercise I wish someone had made me do in my paycheck-to-paycheck years:
Pull up your retirement account and write down three numbers: the total balance, the total fees charged this year, and your target retirement date. Ten minutes, kitchen table, coffee in hand. You don’t need to understand every line yet. You just need to see the shape of what you’re working with — the same way I’d draw a map before planning a route.
Slow and steady. Financial planning isn’t a race, it’s a stack of small, honest decisions — and the first one is just looking at the numbers on the table.